For years, homebuyers focused on one number: the purchase price. Today, the affordability conversation has shifted toward the monthly housing payment. Rising home prices, higher interest rates, insurance costs and homeowners association fees mean buyers increasingly want to know one thing first: What will it cost me each month?
For REALTORS®, that shift presents an opportunity to guide clients through a more meaningful affordability discussion. The goal isn’t to replace the expertise of lenders or financial professionals, but to help buyers and sellers understand the complete financial picture behind a purchase.
Start With Cash to Close and the Monthly Housing Payment
According to Harvey Blankfeld, CRS, Sales Agent, Berkshire Hathaway HomeServices of Nevada, Las Vegas, Nevada, many buyers become overwhelmed by countless financial details when the conversation can be simplified into two essential questions.
First, how much cash will it take to close? Second, what will it cost to own the home each month?
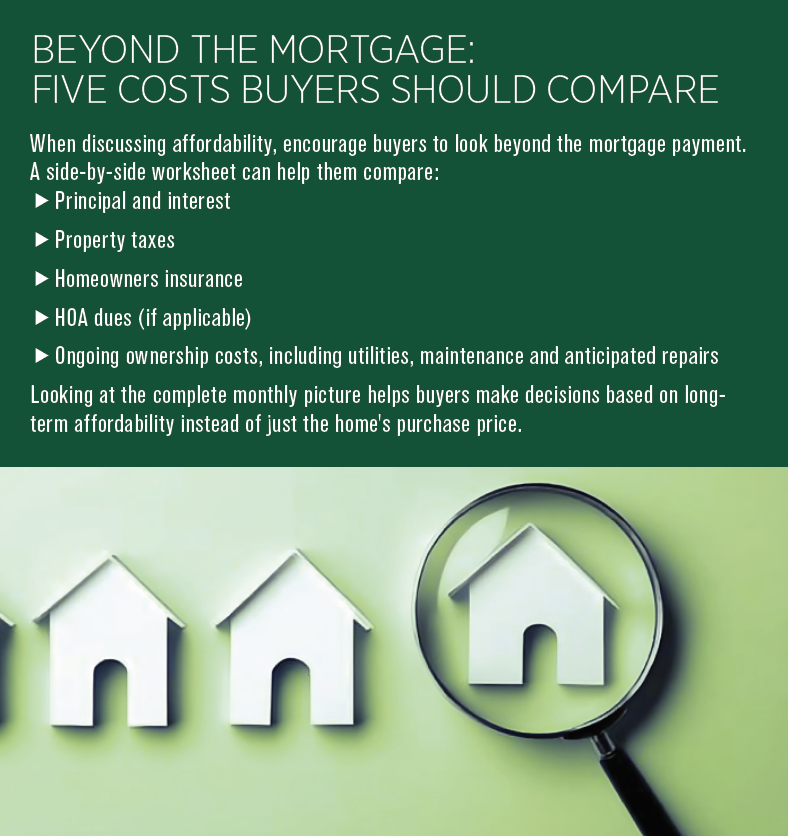
Those monthly expenses extend beyond principal and interest to include property taxes, homeowners’ insurance, mortgage insurance, HOA dues and other recurring costs. Looking only at the list price or even the mortgage payment can leave buyers with an incomplete understanding of affordability.
Blankfeld also encourages buyers to think carefully about financing decisions in the context of their long-term plans. For example, paying additional money upfront to secure a lower interest rate may reduce monthly payments, but buyers should understand how long it will take to recover that investment.
“If you’re only planning to own the home for seven or eight years, does paying significantly more upfront actually save you money?” he asks. Rather than assuming every lower payment represents a better deal, buyers should work with qualified lending professionals to compare financing scenarios based on how long they realistically expect to own the home.
Show the Complete Financial Picture
While the monthly payment has become the language many consumers naturally understand, Monica Neubauer, CRS Certified Instructor at Benchmark Realty in Franklin, Tennessee, cautions against allowing it to become the only number in the conversation.
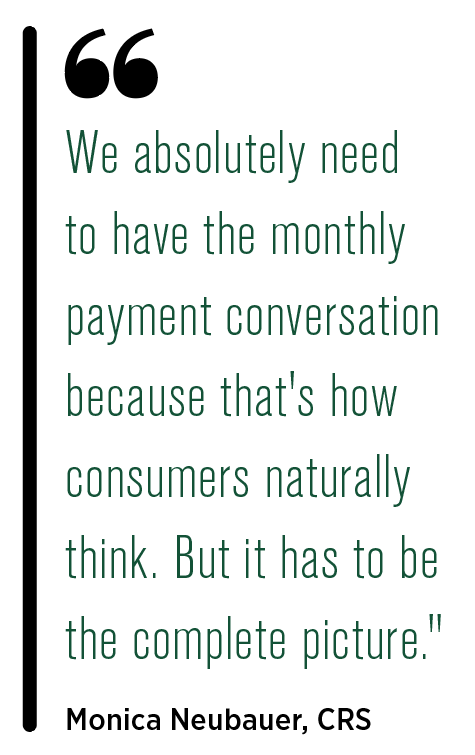
“I’ve become a convert,” she says. “We absolutely need to have the monthly payment conversation because that’s how consumers naturally think. But it has to be the complete picture.”
Neubauer recommends creating a simple worksheet that allows buyers to compare housing costs side by side. In addition to the projected mortgage payment, agents should encourage clients to consider taxes, insurance, utilities, HOA fees, maintenance and anticipated repairs. Seeing those costs together helps buyers understand what homeownership will actually require, not just what the mortgage payment will be.
Just as important, the worksheet creates a record clients can revisit after the transaction, reinforcing expectations and reducing misunderstandings later.
Focus on Comfort, Not Maximum Qualification
For Jeffrey Decatur, CRS, Broker Associate, RE/MAX Capital, Albany, New York, one of the most important conversations happens before buyers ever begin touring homes.
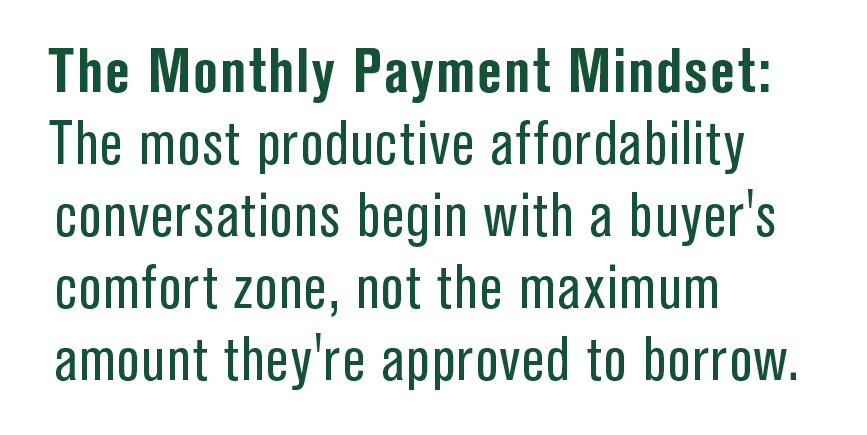
Rather than asking, “How much house can I buy?” he encourages clients to ask, “What monthly payment feels comfortable?”
“Lenders will often qualify buyers for more than they actually want to spend,” Decatur says. Establishing a comfortable monthly payment first allows buyers to search confidently within their own financial boundaries instead of stretching to the highest amount they’re approved to borrow.
Decatur also encourages buyers to think beyond today’s interest rates and consider the long-term value of homeownership.
He describes it as “freezing your housing payment in time.” While taxes, insurance and maintenance costs may increase, the principal and interest portion of a fixed-rate mortgage remains stable. By purchasing a home today, buyers lock in that payment while rents and future home prices may continue to rise.
That perspective helps clients focus less on trying to perfectly time the market and more on making decisions that fit their long-term financial goals.
Stay in Your Lane
Although payment-centered conversations have become increasingly important, all three CRS professionals agree on one point: REALTORS® should facilitate, not replace, the work of lending professionals.
Agents can help buyers identify the questions they should ask, compare affordability scenarios and understand the factors influencing monthly costs. Loan recommendations, financing strategies, tax implications and insurance guidance, however, belong with qualified experts.
Neubauer believes involving lenders early, sometimes even bringing the buyer, lender and agent together for the same conversation, helps ensure everyone shares the same understanding of both qualification and affordability.
The Bottom Line
Price will always matter, but it no longer tells the whole story.
Today’s buyers increasingly evaluate affordability through the lens of monthly cost, while sellers benefit from understanding how those costs influence purchasing decisions. REALTORS® who help clients see the complete financial picture and collaborate closely with trusted lending professionals position themselves as advisors rather than salespeople.
In today’s market, that guidance may be one of the most valuable services an agent can provide.